

Félix Pago
4.5

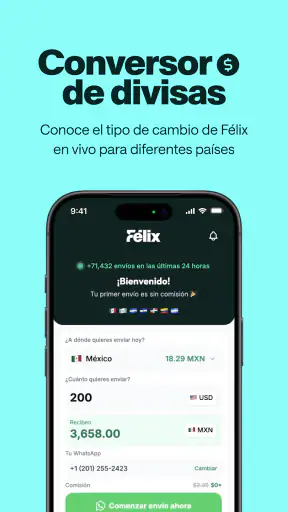
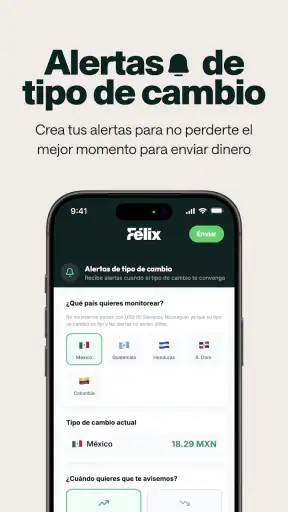
Sending money from the United States can be surprisingly complicated when the person receiving it needs a simple, dependable way to get paid. After spending time with Félix Pago, I came away with a clear impression: this is a focused finance app for people who want to move money without turning every transfer into a research project. It is free, rated for Everyone, and developed by Félix Pago, but its real appeal is not the label or the download count. It is the narrowness of its purpose.
I would recommend it first to someone who regularly sends money from the United States and values a straightforward experience over a large collection of financial tools. I would not treat it as a universal replacement for a bank, a full digital wallet, or an app designed for managing several kinds of payments. Its strength is concentration. When the job is sending money, a focused tool can feel much easier than an overloaded financial app.
What using Félix Pago feels like in practice
The app sits in the finance category, and that matters because it sets the right expectation. This is not a budgeting dashboard, an investment service, or a general-purpose banking companion. I approached it as a transfer tool, and that helped me judge it on the things that actually matter in this situation: how quickly I could understand the process, how much information I had to keep track of, and whether the flow felt suitable for repeating later.
The developer, Félix Pago, presents the product around sending money from the United States. That focus gives the experience a practical quality. Instead of asking the user to learn a broad financial system, the app is easier to think about as a dedicated route for an important everyday task. For a person supporting relatives, paying someone abroad, or sending occasional help, that distinction can reduce the mental effort involved.
Its store presence shows a 4.5 average from around 1.6 thousand ratings, with more than 800 written reviews and over 100 thousand installs. Those figures suggest that the app has attracted a meaningful group of users without making popularity the only reason to trust it. I still think the more useful question is whether its focused approach matches your own transfer habits.
The app is free to install, which lowers the barrier to trying it. That does not mean every possible money movement is automatically costless, and I would still read the transaction details carefully before confirming a transfer. In financial apps, the important figure is often the complete amount the recipient gets compared with what leaves the sender’s side, not simply whether the download costs anything.
A focused workflow is its biggest advantage
My strongest positive impression is that Félix Pago is easier to evaluate than a broad financial app. When an application is built around one central action, I can make decisions with less distraction. I am not looking through investment tabs, card offers, spending charts, or unrelated account tools before reaching the task I actually opened the app to complete.
That simplicity is especially useful for repeat transfers. Imagine a person in the United States sending support to a family member at the end of the month. The first transfer may require more attention because the sender is checking the recipient and the amount. Later, the benefit of a dedicated app is that the same mental pattern becomes familiar: open the service, review the details, confirm the destination, and check the final result. Even when the app cannot remove every verification step, a consistent workflow is valuable.
A less obvious advantage is that a focused transfer app can help separate sending money from everyday spending. If I use one application for purchases and another for remittances, I am less likely to confuse a transfer with a card payment or lose it among unrelated account activity. That separation is not exciting, but it can make personal record-keeping cleaner, particularly for people who send money for a specific purpose.
I also appreciate the possibility of using it for planned rather than impulsive transfers. Before opening the app, I can decide the amount, confirm who should receive it, and keep the purpose in mind. That small habit is useful because transfer mistakes are usually more expensive in time and stress than ordinary shopping mistakes. A dedicated destination makes it easier to treat the action with the attention it deserves.
Where it fits better than familiar alternatives
The usual alternatives fall into several groups. A traditional bank may be the natural choice for people who already manage all their finances there, while a general digital wallet may be more convenient for users who want transfers, purchases, balances, and other activities in one place. Cash-based services can suit people who prefer physical assistance or need a particular delivery arrangement. Félix Pago makes more sense when the main priority is a direct digital sending experience from the United States.
Compared with a bank app, its potential advantage is reduced clutter. A bank application may be excellent for domestic account management but less comfortable when the user’s main concern is sending money elsewhere. Compared with a broad wallet, Félix Pago’s appeal is that it does not need to compete for attention with a long list of unrelated functions. Compared with a physical service, the digital approach is more convenient for someone who wants to initiate a transfer from a phone.
That comparison also reveals the trade-off. A bank or established wallet may be the better option if you need a complete financial record in the same place, want to move money between several types of accounts, or already have a trusted process that works well. A physical alternative may be preferable for someone who is uncomfortable completing financial tasks on a phone. Félix Pago is strongest when simplicity is more important than having every financial feature under one roof.
Small habits that make the service easier to use
I would begin by preparing the recipient’s details before starting. That sounds obvious, but it prevents the transfer from becoming a guessing exercise inside the app. Keep the intended amount and the purpose of the payment clear, then review the recipient information slowly instead of treating the confirmation screen as a formality.
My second tip is to judge the transfer by the complete outcome. A free app download is not the same thing as a free transfer, and a low apparent cost is not useful if the recipient receives less than expected. Before confirming, I would compare the amount being sent, any displayed charge, and the amount expected on the receiving side. This is the most important practical check for anyone choosing between Félix Pago and another service.
Third, I would use a simple personal note after each important transfer. Record the date in your own calendar, the reason, and the amount you intended to send. That is not a built-in feature claim; it is a workflow I recommend because it makes recurring support easier to audit. If a family member asks about a previous payment, you can answer from your own record rather than relying on memory.
For repeat use, I would also avoid rushing simply because the process feels familiar. Familiarity can create overconfidence. The recipient, amount, and purpose deserve a fresh check every time, especially when several people in a family receive support. A focused app reduces distraction, but it cannot replace careful confirmation by the sender.
The limitation I would take seriously
The same narrow focus that makes Félix Pago approachable may make it feel incomplete for experienced financial-app users. If I want a broad overview of my money, detailed budgeting, multiple payment methods, or a single place for all account activity, I would probably look elsewhere. A simple transfer tool is not automatically the best financial home for someone with more complicated needs.
There is also a natural need for caution around any money-transfer application. I would not send a large amount until I had tested the process with a modest transfer and understood the displayed details. That is not a criticism unique to Félix Pago; it is sensible behavior with any service where a mistake can affect another person. The app can make the route clearer, but the user still carries responsibility for checking the destination and final amount.
Another point is that “fast” should be interpreted carefully. The app’s purpose is to simplify sending money from the United States, but speed can depend on the transfer route, the recipient’s situation, and any checks required during the process. I would avoid promising a specific arrival time to someone else until the app shows the relevant information for that transaction. This is particularly important when the money is needed for a bill, emergency, or time-sensitive purchase.
Users who need in-person support may also find a phone-first experience less comfortable. Someone who prefers speaking with staff face to face, handling cash, or receiving extensive guidance at every step may be better served by another type of service. Félix Pago is more convincing for people who are willing to manage the transfer digitally and can verify the details independently.
Who should choose it, and who should skip it
I see the best audience as people in the United States who send money regularly or occasionally and want a dedicated tool rather than a full financial suite. It could suit a sender helping relatives, covering a planned expense, or making a straightforward payment across borders. The free entry point also makes it reasonable to explore before committing to a long-term routine.
It is especially appropriate for someone who dislikes navigating a crowded bank app. If your current method involves several screens that are unrelated to sending money, the focused design may feel like a relief. It is also useful for users who want their remittance activity mentally separated from shopping and daily account management.
I would skip it if your main requirement is comprehensive money management. People who need detailed budgets, investment tracking, broad account aggregation, or a highly established banking relationship may gain more from a full-service financial provider. I would also look at alternatives if the recipient needs a specific payout method that Félix Pago does not support for your situation, or if you require in-person assistance.
Families should decide together how the app fits into their routine. The sender may appreciate the digital simplicity while the recipient may care more about how and when the money becomes usable. Before relying on it for an essential payment, both sides should understand the expected process. That conversation is more useful than assuming that a convenient sending screen guarantees the same convenience at the destination.
Device support and the current release
The current version is 1.1.14, and the app supports Android 7.0 and later. That gives owners of older compatible Android phones a reasonable chance of using it without needing a recent device. I still recommend keeping the phone’s operating system and the application updated when possible, especially for a finance tool where reliability and security hygiene matter.
Because this is a financial app, I would install it only on a phone I control and protect with a screen lock. I would also review every confirmation screen and avoid completing a transfer while distracted or connected to an unfamiliar environment. These are ordinary precautions, but they matter more here than they do with a casual entertainment app.
The Everyone content rating makes the app broadly accessible from an age-classification standpoint. That does not mean every user should send money without guidance. A younger or inexperienced user may still need a parent or trusted adult to explain the amount, recipient, and consequences before using a financial service.
I would treat the version number as a reminder to check for changes over time. Financial applications can refine their screens and transfer flow, so a step that feels familiar today may be presented differently after an update. Before a significant payment, take a moment to read the current wording instead of relying entirely on muscle memory.
My final assessment
Félix Pago is most convincing as a purpose-built sending tool, not as an all-in-one financial app. In my experience, that distinction is its clearest strength. It gives people who send money from the United States a simpler starting point and avoids the distraction that often comes with broader finance applications.
I like the way its focused identity supports repeat use, careful preparation, and cleaner separation between remittances and everyday spending. I also like that it is free to try, available to a broad Android audience, and backed by a solid 4.5 average from around 1.6 thousand ratings. Those details support confidence, but they do not remove the need to compare the final transfer terms or confirm the recipient carefully.
My reservation is equally clear: simplicity has boundaries. If you want deep account management, in-person help, or a complete financial command center, another option may serve you better. If your need is narrower—send money from the United States through a digital, focused experience—I think this app deserves a serious look.
For a friend, I would phrase the recommendation this way: try it with a small, planned transfer, inspect every amount before confirming, and decide whether the workflow feels comfortable for your real routine. If it does, the dedicated approach can be more useful than a feature-heavy alternative. If it does not, the problem is probably not that you need more buttons; you likely need a service whose delivery method, support style, or broader financial tools better match your situation.
4.5
852.00 Reviews
Pros
- Fast money transfers to several Latin American countries
- Clear exchange rates shown before confirming a transaction
- Supports convenient debit card and bank account funding
- Simple interface suitable for first-time remittance users
- Transfer status updates help track payments after sending
Cons
- Availability and features vary depending on your country
- Recipients may need valid identification for certain transfers
- Exchange rates can change outside the app’s control
- Customer support response times may vary during busy periods
- Some transfer methods may include additional service fees


